For many people, personal finance remains one of the most anxiety-inducing areas of adult life — not necessarily because the underlying concepts are especially complicated, but because so few of us are ever formally taught how to manage money well. Budgeting, saving, investing, and debt management are often learned through trial and error, sometimes at considerable cost, rather than through any structured education. The result is a widespread gap between how important financial literacy is and how confident most people feel about it.
The good news is that sound personal finance doesn’t require specialist knowledge or a finance degree. It requires a handful of consistent habits, a reasonable understanding of a few core principles, and the discipline to apply them steadily over time. This article covers four foundational areas: budgeting, saving and investing, managing debt, and protecting your finances against the unexpected — the building blocks of genuine financial control.
Building a Budget That Actually Works
Budgeting has something of an image problem, often associated with restriction and deprivation rather than genuine financial empowerment. In reality, a good budget isn’t about cutting out everything enjoyable — it’s about understanding where money actually goes, so that spending aligns with genuine priorities rather than happening on autopilot.
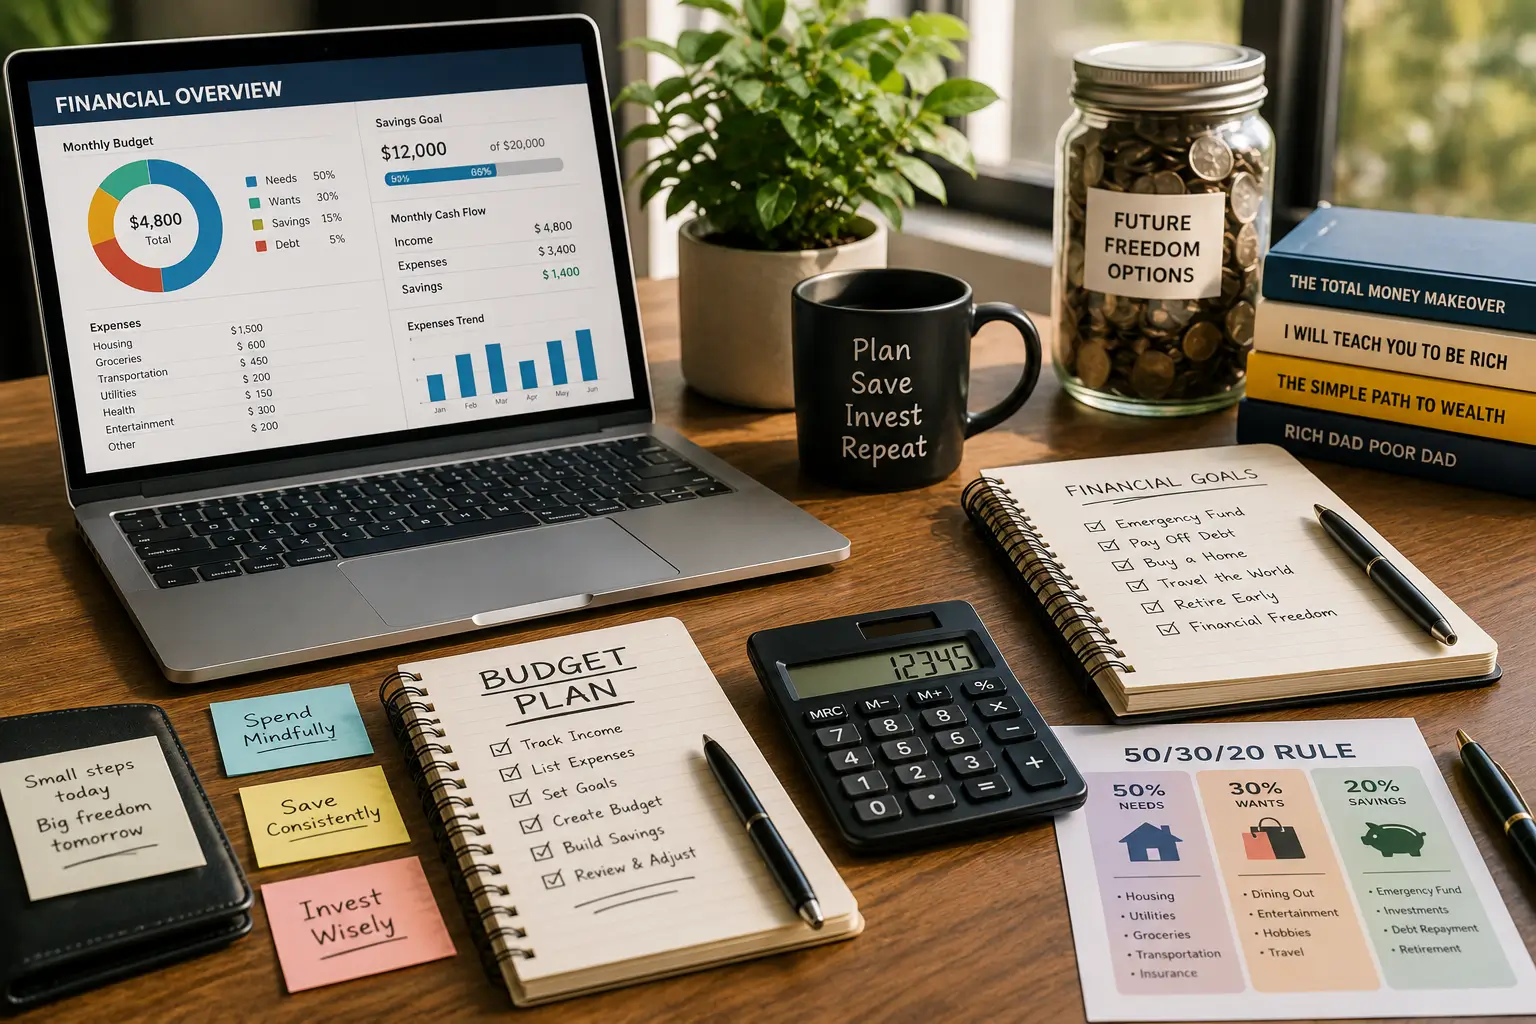
The most sustainable budgeting approaches tend to be the simplest ones. Rather than tracking every single transaction in exhaustive detail — an approach that tends to be abandoned within weeks — many financial experts recommend broader frameworks, such as allocating income across needs, wants, and savings in roughly fixed proportions. This gives enough structure to build genuine awareness without requiring the kind of obsessive tracking that makes budgeting feel like a chore rather than a genuinely useful habit.
Technology has made this considerably easier than it once was. Budgeting apps that automatically categorise spending, track subscriptions, and flag unusual activity have removed much of the manual effort that once made budgeting feel burdensome. That said, the tool itself matters less than the underlying habit — regularly reviewing where money is going, even briefly, tends to produce far better financial outcomes than any particular app or spreadsheet, however sophisticated.
Saving and Investing: Making Money Work Over Time
One of the most consistently misunderstood aspects of personal finance is the meaningful difference between saving and investing and knowing when each is genuinely appropriate. Savings — kept in accessible, low-risk accounts — serve an essential role for short-term goals and emergency funds, where the priority is safety and accessibility rather than growth. Investing, by contrast, is generally more appropriate for longer-term goals, where the potential for growth can outweigh short-term market fluctuations.
Building an emergency fund is widely considered one of the most important financial foundations, typically covering three to six months of essential expenses. This buffer provides genuine security against unexpected costs — job loss, medical expenses, urgent repairs — without needing to rely on high-interest debt to cover the gap, which can otherwise trigger a genuinely difficult cycle of financial stress.
Once that foundation is in place, investing becomes a powerful tool for longer-term financial growth, particularly given how compound growth accelerates significantly over extended periods. The earlier someone begins investing, even in modest amounts, the more time their money has to benefit from this effect. For many people, low-cost index funds offer a genuinely sensible entry point into investing — providing broad market exposure without requiring the time, expertise, or risk tolerance that individual stock-picking demands, and consistently outperforming a large proportion of actively managed alternatives over the long term.
Managing and Escaping Debt
Debt carries a certain amount of stigma, but it’s worth recognising that not all debt functions the same way. Distinguishing between what might be called “good” debt — a mortgage, for instance, tied to an appreciating asset and generally low interest rates — and high-interest “bad” debt, like credit card balances carried month to month, is an important first step in developing a genuinely sound debt management strategy.
For those dealing with multiple sources of debt, prioritisation matters considerably. Two common strategies tend to dominate financial advice on this topic: the “avalanche” method, which prioritises paying off the highest-interest debt first to minimise total interest paid, and the “snowball” method, which prioritises paying off the smallest balances first to build psychological momentum. Both are mathematically valid approaches, and the right choice often comes down to which one a person is genuinely more likely to stick with consistently over time — the best strategy, in the end, is the one that actually gets followed through to completion.
Beyond individual debt repayment strategy, it’s worth acknowledging that financial stress from debt is often compounded by isolation — a reluctance to seek advice or discuss the situation openly, whether with a partner, family member, or financial professional. Genuine financial recovery often benefits enormously from that same kind of reliable support and honest conversation that underpins so much of our overall wellbeing, rather than attempting to navigate serious financial difficulty entirely alone.
Protecting Your Finances Against the Unexpected
Sound financial planning isn’t just about growth — it’s equally about protection against the inevitable surprises that life throws up. Insurance, often treated as an unwelcome recurring expense, plays a genuinely essential role in financial resilience, providing a safety net that prevents a single unexpected event from derailing years of careful financial planning.
Health, income protection, and life insurance each serve distinct but complementary purposes, and the right combination depends heavily on individual circumstances — dependants, existing savings, employment type, and overall risk tolerance all factor into what genuinely makes sense for a given situation. Many people significantly underestimate their actual need for this kind of protection, particularly income protection, which remains one of the most overlooked forms of insurance despite protecting against one of the most financially devastating scenarios: a sudden inability to earn.
Estate planning, too, deserves more attention than it typically receives, particularly among younger people who often assume it’s a concern reserved for later in life. Having a clear, legally sound will, understanding how assets will be distributed, and considering appropriate powers of attorney are all part of genuinely responsible financial planning — steps that, while sometimes uncomfortable to think about, provide real protection and clarity for both the individual and their loved ones. As with so much of personal finance, the food and drink choices that shape daily spending often represent one of the largest and most flexible categories in any household budget, making it a natural starting point when looking for genuine savings.
Ultimately, taking control of personal finance isn’t about achieving perfection or eliminating every source of financial stress entirely. It’s about building consistent habits across budgeting, saving, debt management, and protection — habits that, layered together over time, create genuine financial resilience and, with it, a meaningfully greater sense of control over one’s own life.